Kansas City Real Estate Investing: Cash Flow, Appreciation, and the Race to 10 Doors
When investors ask me where they should buy rental property in Kansas City, my answer usually starts with another question:
What are you trying to accomplish?
Because there isn't one universally "best" place to invest in Kansas City.
A $100,000 rental on the east side of Kansas City is a completely different investment from a $300,000 house in a stronger suburban neighborhood. One might produce better cash flow. The other may offer stronger appreciation, a different tenant profile, and potentially fewer headaches.
Neither strategy automatically makes the other wrong.
The important thing is understanding what you're buying, why you're buying it, and how that property fits into your long-term investment strategy.
If You Have $150,000, Don't Automatically Buy a $150,000 House
Suppose you have $150,000 available to invest.
One option is simple: buy a $150,000 property with cash.
You're debt-free. You collect rent. It feels safe.
But you've also tied almost all your available capital up in one property.
If a furnace goes out, there's a major plumbing problem, or the property needs an expensive turnover, where does that money come from?
That's why one of my first questions would be:
Is that $150,000 all of your available investment capital?
If it is, I wouldn't want every dollar going toward the purchase.
You need reserves.
And I'd also look for opportunities where we can make the capital work harder.
For example, perhaps we find a distressed house for approximately $100,000. We put another $50,000 into renovating it, and now we've created a property worth approximately $200,000 or more.
Instead of simply buying an asset, we've created equity.
Depending on the financing available and the finished value, we may then be able to refinance the property and recover the capital invested.
Now we can start looking for the next property.
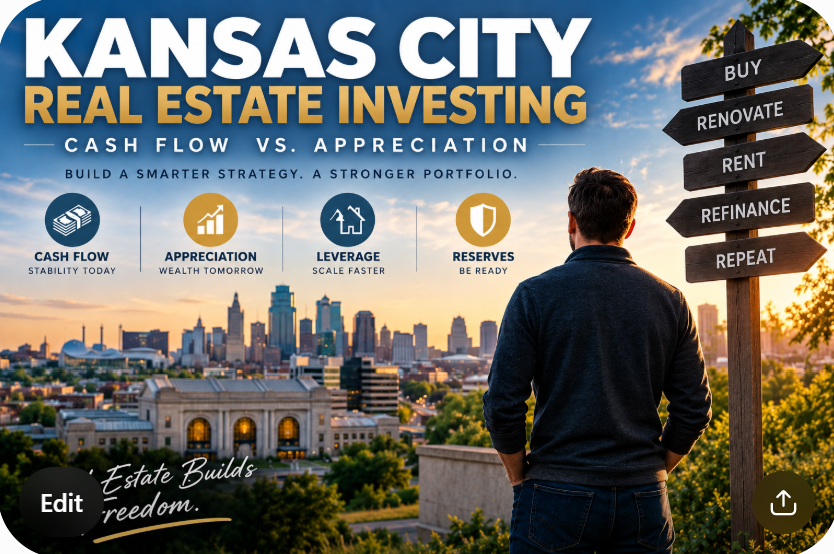
That's the basic idea behind the BRRRR strategy:
Buy. Rehab. Rent. Refinance. Repeat.
The objective isn't simply to own one rental.
It's to develop a repeatable system for building a portfolio.
Kansas City Real Estate Is a Risk-versus-Reward Decision
This is where geography becomes important.
There are parts of Kansas City and Wyandotte County where properties can still be purchased relatively inexpensively.
That can make the numbers look extremely attractive.
Imagine purchasing a property for around $100,000 that rents for $1,300 per month.
At first glance, you may love the rent-to-price ratio.
But those numbers don't tell you everything.
Depending on the property and neighborhood, you may have a greater chance of dealing with tenant problems, nonpayment, larger turnovers, maintenance issues, or other expenses.
You also may not experience the same long-term appreciation that you could see in a stronger neighborhood.
It's similar to investing in the stock market.
Potential reward and risk tend to travel together.
At the other end of the spectrum, perhaps you buy a $300,000 house in a stronger neighborhood.
You put 30% down.
Your monthly cash flow may be considerably lower than it would be on the cheaper property.
But you're making a different bet.
You're looking at the quality and stability of the location, potential appreciation, equity growth, tenant profile, and the long-term value of the underlying asset.
That's why asking, "What's the cap rate?" isn't enough.
I want to know what you're trying to accomplish with the property.
Where Can You Find Cash Flow AND Appreciation Around Kansas City?
There isn't just one answer.
There are opportunities throughout the Kansas City metro depending on the property, price, financing, and exact neighborhood.
Areas I'd investigate can include:
Independence
Gladstone
Excelsior Springs
Shawnee
Olathe
Lee's Summit
Grandview
Belton
That doesn't mean every house in those cities is a good investment.
Far from it.
You still have to understand the individual neighborhood, the property itself, the purchase price, expected rent, condition, tenant pool, and your financing.
But there can be opportunities in these markets where an investor doesn't have to choose entirely between cash flow and appreciation.
And there's another factor I think investors sometimes underestimate:
The quality of your product matters.
Put an A-Quality Product in a B- or C-Level Location
If you buy an inexpensive rental and treat it like an inexpensive rental, don't be surprised when you get inexpensive-rental problems.
If the house looks like a dump, it's going to be harder to attract and retain the type of tenant you want.
I'd rather create a product that stands out.
Even in a B-minus or C-level area, I want the house itself to feel like an A-level product for that neighborhood.
Make it clean.
Make it attractive.
Fix things properly.
Give people a home they're proud to live in.
Yes, you'll probably spend more money upfront.
But now you're positioning yourself to attract a stronger tenant within that particular renter pool.
A better product combined with good tenant screening can potentially mean a better rental experience and longer tenancy.
And that can have a major effect on your actual return.
Because your spreadsheet doesn't experience a turnover.
You do.
Cash Flow Isn't Spending Money
Here's another idea I wish more new investors understood:
Cash flow isn't necessarily income you should immediately spend.
Especially when you're building your portfolio, I look at cash flow as protection.
Eventually, something will happen.
A furnace will go out.
An air conditioner will fail.
You'll have a turnover.
There will be plumbing problems.
Something you didn't budget for will eventually cost you money.
Suppose a furnace replacement costs you $4,000.
Where does that $4,000 come from?
If your investment strategy depends upon every property operating perfectly every month, you don't have much of a strategy.
That's why cash flow matters.
But there's another reason I care so much about it during the early stages of portfolio building.
Get to 10 Doors
One of the numbers I like investors to think about is 10 doors.
Get to 10 doors as quickly as you responsibly can.
People sometimes hear that and think, "I don't know how I'm supposed to get to 10 properties."
That's fine.
Most people don't know how to solve a Rubik's Cube either.
Then they learn the process.
Real estate investing is similar.
You don't have to know how to buy all 10 properties today. You need to understand how you're going to acquire the next one, and then repeat a sound process.
Here's why 10 matters.
Suppose you eventually own 10 rentals and each one produces $200 per month in cash flow after your regular operating expenses.
That's:
10 properties × $200 = $2,000 per month.
Now your portfolio is producing $2,000 each month that can help strengthen your reserves and absorb unexpected expenses.
One property's furnace goes out?
The portfolio helps carry it.
One property has a rough turnover?
You have nine other properties contributing.
That's very different from owning one rental where one major repair can wipe out a large portion of the year's cash flow.
The portfolio begins supporting itself.
Before 10 Doors, I'd Focus Heavily on Cash Flow
That leads to another question:
Should your fourth or fifth property be a cash-flow investment or an appreciation investment?
My answer is pretty simple.
You're not at 10 yet. Work on cash flow.
That doesn't mean I'd buy a bad property just because a spreadsheet says it cash flows.
It doesn't mean ignoring appreciation.
And it certainly doesn't mean ignoring location, property condition, or tenant quality.
But during the portfolio-building stage, I want the investor creating enough financial strength that the portfolio can withstand problems.
Once you have that foundation, you have more flexibility.
You can start making investments that may produce less cash today because you're pursuing stronger appreciation or equity growth tomorrow.
What Happens After You Build the Portfolio?
This is where real estate investing gets really interesting.
A lot of investors assume the ultimate objective is to eventually sell their rental properties.
I'm not convinced that's always the right way to think about it.
Selling an occupied rental can create complications. Depending on the property's condition, tenant situation, deferred maintenance, and buyer pool, you may not capture the same price you potentially could from a properly prepared property marketed more broadly.
More importantly, selling means giving up the asset.
Consider another possibility.
Imagine you've built a 10-property portfolio.
For illustration, suppose you've used 15-year mortgages and you're eight years into those loans.
You've potentially created equity in multiple ways:
Your tenants have helped pay down your mortgages.
The properties may have appreciated.
Improvements you've made may have increased their values.
You could now be sitting on substantial equity.
Instead of automatically selling the properties, you could explore whether refinancing some of that equity makes sense.
Suppose, purely as an example, you were able to access $500,000 from your portfolio.
What could you do with it?
Maybe your next purchase isn't another single-family house.
Maybe you're looking at a 15-unit property in a stronger neighborhood.
Now you've taken the equity created by your first portfolio and used it to acquire another income-producing asset.
Your original properties continue operating.
Your tenants continue paying rent.
Your mortgages continue getting paid down.
Your assets potentially continue appreciating.
And now you've added another source of cash flow.
That's when you begin to see the difference between simply owning rental properties and actually building a real estate portfolio.
Don't Ask Me Where to Buy Until You Know What You're Building
So when somebody asks me:
"Where should I invest in Kansas City?"
I'm reluctant to immediately give them a city or neighborhood.
First, let's talk about you.
How much capital do you have?
How much needs to stay liquid?
What reserves do you have?
How comfortable are you with debt?
How much risk can you tolerate?
Do you need cash flow today?
Are you trying to build wealth 15 years from now?
How many properties do you ultimately want?
Are you willing to deal with the additional risks that can accompany less-expensive properties?
Or would you rather leave more money in a higher-priced property in exchange for the characteristics of a stronger neighborhood?
Those answers determine what a "good investment" looks like.
Cash flow gives you staying power.
Equity gives you options.
Appreciation builds wealth.
Leverage can help you scale.
And a great investment strategy understands how all four work together.
The goal isn't simply to buy a rental property in Kansas City.
The goal is to build a portfolio that can eventually work harder than you do.
The examples in this article are illustrative and are not projections or guarantees of investment performance. Real estate investments involve risk, and financing, taxes, maintenance, vacancies, transaction costs, market conditions, and individual circumstances should be evaluated before making an investment decision.